MOVE Index and VIX Index

MOVE index was developed by Merrill Lynch to measure implied volatility of US Treasury markets. It is a yield-curve weighted average of normalized implied volatility of 30-day options. The index has been in existence for several years now, however it is seldom discussed, either in itself, or in relationship to the VIX. What I am interested in is if volatility in the treasury market can forecast volatility in the equities.


The images above show the MOVE and VIX indexes for the last 5 years, and ratio=VIX/MOVE. While it appears from the plot that MOVE started increasing much earlier in apparent anticipation of 2008, corresponding to low points in the ratio plot, subsequent rise in the VIX was much more severe than that of the MOVE.

To get a better view of the relationship between the two indexes I conducted a number of regression-based tests. The results all indicate that indeed MOVE index can help predict future level VIX. The simplest model for the VIX level based on the MOVE is
VIX = EXP(-1.84+1.06*LN(MOVE))
You can type the formula directly into Excel. MOVE index closed yesterday at 98.70, implying VIX price of 20.65, compared to the last VIX price of 20.88.

Week in volatility, VIX forecast analysis

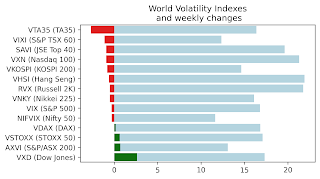
Equity indexes traded in a range this week, ending almost unchanged / slightly up over week. However VIX futures fell strongly across the board, declining an average 1.76 points, which VSTOXX futures fell 1.05 points. The sharpest decline was in Nov VIX futures (current front month, following October expiration 5 days ago) that feel almost 3 points from 24.05 to 21.10.


Despite this sharp decline I continue making bearish bets. It is true that we are in a low volatility regime, but my own research indicates that such low-volatility regimes are usually persistent, and provide a good opportunities for selling volatility. I plan to write more about this when I have more time.

October futures and options expired last Wednesday, settling at 21.41 . My forecast made last month for October expiration was 22.62 (error=1.21) vs market forecast 25.55 (error=4.14). I do not have yet forecast for Nov expiration, because of some software issues, however I plan to update the blog as soon as I have them.

Good luck traders, and hedge your deltas!

STLFSI and VIX

First off, let me apologize to all my readers for infrequent posting. I was very busy moving to NYC and just did not have the time to follow up on all the news in the volatility universe or questions that you emailed me. Also, I would like to thank my friend Ethan for all his help.

Last week vixandmore wrote two excellent posts about stress indexes, namely St. Louis Fed Financial Stress Index and Kansas City Financial Stress Index, here and here. I previously mentioned STLFSI and its relationship with VIX here.

I don't have any criticism for the indexes, however I think that practically they are useless - STLFSI is published weekly with at least one week lag (right now the latest release is dated 9/24/2010), and KCFSI is published once per month. If you're trading, such delays are simply impractical, and reconstructing indexes from raw data to create daily values seems like a lot of work.

Good luck traders, and hedge your deltas!

Week in Volatility

Beside market weakness on Wednesday and Thursday volatility indexes remain almost unchanged for the week. We're only few trading days away from October, but futures and skew in vol options remain cheap. The 22.5/25/27.5 fly I put on a while ago is not working well - even though the futures approached the sweet spot, marks have barely moved - probably because of the skew. Now I'm trying to roll the fly somewhere lower.

I am still on vacation, so there probably will be no other posts this week.


Crude Oil & Gold Volatility Futures to Trade on CME

After announcing new commodity volatility indexes back in March, CME announced they're actually launching futures and options on NYMEX WTI and COMEX Gold volatility in the fourth quarter. This is to be followed by launching volatility derivatives on Soybeans and Corn in the first quarter of next year.

There is no exact schedule of product launch - whether CME will launch futures first, and then introduce options, or launch futures and option simultaneously. I hope that the new products will succeed, although I have my reservation given many failures in volatility derivatives. What makes these contracts different is that GVX and OIV would be the first commodity volatility derivatives to be listed.

CME product webpage here, including historical data for all new indexes. Press release here.

Australian Volatility Index S&P/ASX 200 VIX

"The S&P/ASX 200 VIX will be an end-of-day index that reflects investor sentiment about the expected volatility in the Australian benchmark equity index, the S&P/ASX 200." The exchange will start disseminating the index (ticker XVI) on Sep 23, 2010. The index follows the same methodology as the VIX.

Exchange page on the index here, including historical data for the new index . Press release here.

P.S. Bloomberg symbol for S&P/ASX 200 VIX is SPAVIX.

VIX as a Commodity

There is an excellent article on commodities modelling that limns many of common features between VIX derivatives and commodity derivatives:

VIX - underlying not tradable / not possible to practically replicate
Commodities - all liquidity in the forwards, not spot

VIX - no pure arbitrage plays between different months
Commodities - limited arbitrage opportunities depending on storage

VIX, Commodities - stable long maturities, volatile near maturities

VIX, Commodities - volatility is backwardated

VIX - call skew, dominated by consumers
Commodities - call skew in products like NG

VIX, Commodities - spiking behavior, difficult to model with markovian models, requires extreme mean-reversion (much greater than in historical data), or regime switching (VIX seem to be well-partitioned into 3 regimes)

Weekly market report

Wall st delivered a mixed bag of news with VIX, VNKY, and VSTOXX and their underlying markets almost unchanged. VXD - volatility index based...