Case solved: no arbitrage

Apology to the readers - I got too excited and did not read prospectus carefully enough. The fair value of XXV should be calculated as $20 * (1-return on VXX). I used Aug 4, 2010 as a reference price, since it is the first trading day for XXV, however prospectus says that the reference price should be the one from "inception date" of July 16th. On that date VXX closed at 109.48 (adjusted for split) , creating the following formula:

simulated XXV = $20 * (1 - (VXX-109.48)/109.48 )

which results in values that are fairly close to actual XXV values. See prospectus on page PS-7 for the proper formula.


For more exact calculation I reverse-engineered a better reference price of 108.03, which is probably close to the VWAP price of VXX on that day, making the formula

simulated XXV = $20 * (1 - (VXX-108.03)/108.03 )

This answered my previous question of why XXV return was lower than VXX - it was not, I just was using the wrong reference price. The second question was regarding volatility - XXV has about half of daily volatility of VXX. Here again the explanation is fairly simple - as VXX goes lower its dollar volatility decreases, and dollar volatility of XXV decreases, but in % terms XXV volatility decreases because XXV is now at a higher price.

In fact I can make a prediction that at some point as VXX goes lower, XXV will approach its maximum value of $40 slowly, penny by penny.

I want to thank all the readers who emailed me with their comments, especially William W. for his helpful explanations!

VXX - XXV Arbitrage ?

Happy New Year, traders! Hope that 2011 will be a healthy and prosperous for you and your loved ones!

I don't watch XXV on a daily basis, but few days ago noticed an interesting pattern: since XXV started trading few months ago it did not rise as much as VXX fell, in other words, XXV did not exactly replicate "short VXX" I don't know why it has happened - was it because of transaction costs, or some other reason - I don't have an explanation, but looking at some basic stats I think it maybe an idea for a trade. Before I proceed I must disclose that I don't intend to put this trade on myself as I am busy with my main trading activities, but I do believe this can be an actual trading opportunity for someone else. Ok, here's the numbers: since 8/4/2010 VXX had an average daily return of -0.75%, and XXV +0.31%, total of 0.44%. That means that if an investor were to enter a portfolio of short VXX and short XXV without any costs, they could capture a daily return of 0.44%. The pattern persist across the time - in Dec it is 0.89%, Nov 0.12%, Oct 0.76%, Sep 0.44%. In August the number is -0.09%, but I think that is because of the excess volatility in the first few days of XXV trading. A trader with ability to borrow these two instruments can short both VXX and XXV, pay short interest (very reasonable compared with ETN gains) and walk away with a profit. Daily rebalancing is not required for this to work, since XXV is not a daily inverse VXX, but rather simple short VXX.

What is the reason for XXV relative under-performance? Bid-ask and financing charges seem to have only a minute effect on profitability, certainly not the ~20% difference in less that half of a year. What is more puzzling is that volatility of XXV is about half of that of VXX. I thought that perhaps XXV is under-leveraged compared with VXX, possibly because of higher margin requirements on short futures, however I could not find it in the prospectus. Ideas, explanations, criticism? Good luck traders, and watch your deltas!

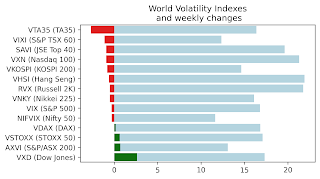
Week in Volatility

After a sharp decline last week, VIX traded in a 15.50-16.50 range, surprisingly rising on Thursday , which was the last trading day of the week. Given that many exchanges around the world will be closed tomorrow, and light trading around the New Year I expect the spot volatility indexes to remain low, while the term structure of futures to be high. This all should put some pressure on VXX, however I don't have a forecast. My forecast for the VIX to be in little higher in 16 - 17 range.


For January expiration my forecast is for 17.66 +/- 3.85 vs market forecast (based on futures and options implied volatility) of 19.80 +/- 4.53.


Week in Volatility

While stock and volatility indexes remained choppy most of the week, VIX took a beating on Friday, declining from already technical low of 17.50 to 16.00. I am sure that part of the decline is to be explained by lowered trading activity around holidays and non-trading days (VIX is calculated in calendar days, making it low biased) however that does not explain the whole story - for example VSTOXX that has similar calculation and holidays actually rose on Friday. So I will do some cross-asset comparison: GVZ - gold volatility also dropped on Friday to a new low, MOVE index that is tracking interest rate volatility is at 1-year high, JPMVXYG7 index that tracks implied volatility of G7 currency options is somewhere in between its 1-year high and low. My forecasts (and my trading positions) are for VIX to increase in price.


VIX Falls

As I'm writing this VIX is trading at ~15.60, very close to it annual low of 15.23 back in April. This level is obviously significantly below what I expect a month ago, but also lower than investor expectations. The front month futures expiring on Wed, Dec 22 that have only 2 full trading days until expiration are still relatively juicy at 17.30! Of course the big question on everyone's mind is what is next for the market and for the VIX. While the future is uncertain, I think that VIX has entered a low-volatility regime (see my post here). I think economic uncertainty will not allow long-term VIX futures to fall much lower (back months are about 25) , which means that term structure premium is likely to remain high. If I'm correct in my hypothesis, we can see a steady decline in VXX due to increased rolling costs. Good luck traders, hope everyone has a good expiration!

VSXX Disappoints European Investors

I have written before about VSXX - an ETF that tracks pan-european VSTOXX volatility index, European equivalent of VXX. In that post I described how VSXX performance may be different, because of the flatter term structure of VSTOXX volatility futures, that will translate into lower rolling costs, and better performance for VSXX investors, at least compared with VXX. I also noted that traders may take advantage of this difference in a relative value trade. When I wrote the post, VSXX was trading for only two months, however now after seven month of trading it is becoming clear that my investment hypothesis not deliver, and VSTOXX futures markets became more economically efficient.

Here's the chart of what happened: VSXX originally listed at around the same Euro value as the index, however in the last few weeks VSXX is about 70% of VSTOXX index.


If you looked at the relative plots of VIX and VSTOXX with their futures indexes (on which ETFs are based) it is clear that historically VSTOXX futures index did much better job in tracking index levels than the VIX futures index. To understand the dynamics, I have performed the following two regressions:

return on SPVIXSTR ~ α + β * return on VIX, and
return on VST1MT ~ α + β * return on VSTOXX.

Using the data for the last five years, in the first case α = -0.0016174 (t=-3.2335) α * 252 = -40% per year negative "premium" for the VIX futures index. In the second case α = -0.00021095 (t= -0.30876, intercept not statistically significant) α * 252 = -5% per year negative "premium" for the VSTOXX futures index.

However when I used data for the last half year - approximately since VSXX came into existence, intercept values became much closer to each other, at -0.006422 -0.0047229 for VIX and VSTOXX respectively. These numbers by themselves imply a very negative risk premium, they are at least the same order of magnitude, as opposed to alphas from the 5-year regressions.

It seems that there is an equal demand now in Europe for volatility protection, which brought returns on the futures indexes in line with each other. In fact VSXX and VXX followed very similar paths (normalized returns in local currencies)


In conclusion: what was hoped to be a unique investment opportunity for European investors seized to exist. Once a trading instrument is in the market traders work quickly to make profits and eliminate inefficiencies.

Russian Volatility Index

It is official, yesterday RTS announced (eng, rus) that they will start disseminating the first "official" volatility index based on the Russian options market.

I blogged earlier about Russian VIX here, however at this time ОТКРЫТИЕ removed previous links to the construction of the volatility index, and I could not find any details on the RTS website. I assume that either way the exact methodology will feature two modifications to the VIX algorithm, namely parametric interpolation of the volatility skew to deal with relatively small liquidity in the market, and nonlinear weighting of the months, because expirations are sparse, and do not always bracket 30-day maturity.

RTS stated that they will start disseminating the index on Dec 7th. Bloomberg ticker for the index is RTSVX.

Weekly market report

Wall st delivered a mixed bag of news with VIX, VNKY, and VSTOXX and their underlying markets almost unchanged. VXD - volatility index based...