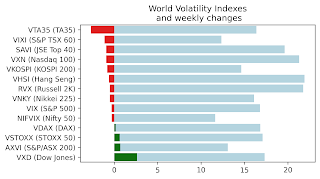
RTSVX Futures Launched


RTS, the leading derivatives exchange in Russian Federation launched trading in futures tied to RTSVX - Russian volatility index. The futures started trading on the June 1st, and the first contract (June) expired last Tuesday. Although it is probably too early to tell, the contract seems to be a success - daily volume is over 100 and open interest in thousands. Press release (eng, rus).

What is really interesting about the contract is that it is denominated in USD, with one point equals to $20, such that minimal tick 0.05=$1 . Default expiration of the futures contract is seven days before RTS expiration. Contract specifications are available here.

Right now only two months are listed - July and September, but RTS will probably list more based on demand. Because the contracts are denominated in dollars, trading provides an interesting opportunity for statistical trading between RTSVX and VIX ( although with significant execution risk since trading hours don't overlap ) , as well as trading between RTSVX  and VSTOXX futures ( with currency risk between USD and EUR ) My hope is that the success of RTSVX will lead other world exchanges to launch futures on their volatility indexes, such as INVIX futures in India, and XVI / SPAVIX futures in Australia.

More details on RTSVX index calculation methodology are available here (eng, rus).

XIV - the first 6 months

XIV ETF has almost doubled since it launch about half a year ago. If you invested in the beginning and made a lot of money - congratulations! But the big question is: can we expect the same excellent performance from XIV going into the future? To answer this question I look at the SPVXSP index - the underlying for both VXX and XIV for the last 5 years. I take the values of the index and simulate hypothetical performance for the ETFs (starting values normalized to 100)


While the last half-year for the XIV have been excellent, XIV had a huge drawdown losing over 80% of its value at one point. In the five years since June 2006 to January 2011 XIV was flat, and despite its excellent performance in the past half-year XIV still would not have recovered from the drawdown.There is obviously a lot of risk in XIV that recent history does not account for. Geometric annualized return for the index (like-VXX) is -37.47%. Geometric annualized return for the daily inverse (like-XIV) is 12.77%

EDIT: See my new post on XIV.

More Commodity Volatility Indexes

CME announced that they will start disseminating two more volatility indexes - one for corn and another for soybeans. Current commodity volatility indexes are - GVZ/GVX for gold, OIV/OVX for crude, VXSLV for silver, and SAVI white maize index calculated by Johannesburg Stock Exchange. Since CME failed to generate any volume for their volatility contracts, and CBOE's recently lauched GVZ futures and options volume is still very small (and not growing) it is very likely that no derivatives will be listed on these instruments.
See more commodity volatility indexes here.

VOLT ETF / Voltage ETF Update

Since I've blogged about VOLT ETF few weeks ago, I was able to obtain official Nomura document about the product. The document is very thorough, explaining in detail  the phenomenon of positive correlation between vol of vol and volatility level. VOLT uses dynamic allocation, and trades (rather than invest) quite aggressively. Robustness of the strategy is also addressed by selecting different lookback windows for estimating vol of vol. Fwiw I would love to see the same analysis done using more efficient intraday realized vol of vol measures.

While it sees that the strategy is sound, and provides for a good hedge for a long portfolio, the strategy is complex and it is hard to estimate the potential of strategy failure in the future. My suggestion is if you're a trader to use the research (correlation between vol of vol and volatility) for your own strategies, and if you're an investor consider a small allocation because of the negative effect of the fees and trading costs.

Nigerian Stock Exchange WTF

Over the weekend I came across an article about Nigerian Stock Exchange introducing options and futures trading. While trying to find out more information I saw the following quote on the Exchange's website:

"Integrity is the watchword of The Stock Exchange. Market operators subscribe to the code “Our word is our bond”. Thus, public trust in the Nigerian stock market has grown tremendously ...  The Stock Exchange’s 39-year history is devoid of any fraud, shocks, scandals or insider dealings."

ORLY?

Week in Volatility

Markets fell, and VIX rose substantially on Wednesday. What is unusual that is week over week long-term futures were practically unchanged, slightly higher for VIX, and slightly lower for VSTOXX futures. GVZ volume is not growing - with zero futures and 40 options contracts traded in the last week. It also looks like the bid-ask spreads on GVZ options have widened since the contract listed. Oh well...


What do YOU think? Volatility Forecasting Challenge!

Every month, around the VIX expiration I publish my forecasts for the next month. This time I would like to do something different – for you to join me in this exercise. Email me your VIX forecast for July 2011 expiration before June 15th 2011, and if your forecast is the closest to the July official VIX settlement (VRO) I will paypal 100 USD to the winning email address.

The rules are simple: your forecast is a single number (not a range) for the settlement value of VIX (VRO) on Jul 20th , 2011. One entry per person, and I reserve a right to remove any entry that I consider to be suspect. Your email addresses will not be used for any communication from me, or given to a third party – I love my readers and do not intend to spam them.

Weekly market report

Wall st delivered a mixed bag of news with VIX, VNKY, and VSTOXX and their underlying markets almost unchanged. VXD - volatility index based...