Opalesque.tv has two most interesting interviews: first, from 2012 with Michael Wexler of Maple Leaf, and second , posted earlier this month, with Dr Andrew Cumming of Blackheath Volatility Arbitrage. It is not often that you hear detailed interviews from volatility arbitrage managers, so I thought to post the links in case my readers missed it.
Volatility trading is complex, and there are many more volatility strategies than there are equity strategies, but the funds mentioned above do run a similar core strategy - both sell ATM options and buy / overbuy wings (similar strategy is purportedly traded by ex-Nassim Taleb's hedge fund). The first payout strategy is fly - which is easy to understand as short vol position; the second - short ATM longs extra wings, looks like letter W with peak at the money, and extra wings on the side. The strategy is called dragonfly, and it is much harder to provide a simple explanation. It pays off in a really calm market, loses money in a moderately volatile market, and makes money in very very volatile conditions. The payoff is obviously highly nonlinear.
Both funds are extremely diversified across all asset classes, and geographic markets. Michael Wexler notes that equities is probably the most difficult asset class for short vol, given the high level of cross-correlations at times of crisis, and competition.

Notes From Academia: Exercise Boundary Violations in American-Style Options
Here is the link to the research paper - Exercise Boundary Violations in American-Style Options: The Rule, not the Exception
The findings are not at all surprising: options market makers do not like to provide tight quotes for ITM options, especially high-delta options, because of pick-off risk. If market makes a sudden move, HFT stock traders, or options market makers with faster infrastructure can quickly trade against a slower market maker, locking in free premium. OTM options don't move as fast, and are not as risky from this angle.
So it is only natural that bids are below the exercise boundary. Majority of option traders know as much - if only 11.5% of volume is below intrinsic value, 88.5% presumably do not make that mistake.
Abstract: An exercise boundary violation (EBV) occurs when the current bid price for an American option in the market is below intrinsic value. A seller at this price leaves money on the table and the buyer receives an arbitrage profit. In a liquid market, competition among dealers should drive up the bid prices and eliminate the arbitrage. An analysis of intraday data shows that EBVs are the norm, not the exception, with near-term in-the-money equity calls and puts the most affected. In March 2010 48.6% of all in-the-money call options had EBV bid quotes and 11.5% of trading volume in those options occurred below the intrinsic value, costing the sellers an estimated $39 million. EBVs are highly persistent throughout the day, making it rational to liquidate an option by exercise rather than selling it in the market, in sharp contrast to textbook theory. Our empirical results show early exercise is strongly related to an option's EBV.
The findings are not at all surprising: options market makers do not like to provide tight quotes for ITM options, especially high-delta options, because of pick-off risk. If market makes a sudden move, HFT stock traders, or options market makers with faster infrastructure can quickly trade against a slower market maker, locking in free premium. OTM options don't move as fast, and are not as risky from this angle.
So it is only natural that bids are below the exercise boundary. Majority of option traders know as much - if only 11.5% of volume is below intrinsic value, 88.5% presumably do not make that mistake.
Volatility of Average
Different commodity including some volatility and bitcoin futures settle to an average value. For example VSTOXX settles to 1 minute sampled average value of the index in the last half hour of trading, Bitmex XBT/USD futures settle to 1 minute sampled average value of the last two hours of trading, Atlas ATS BTC/USD futures and options settle to a 24 hour average of the last calendar day of the month.
Correct modelling of this is interesting for both options and futures pricing, as average process has obviously less volatility than "regular" process. How much less? Well, apparently I fell asleep during a class because I have no recollection of the formula until I recently researched it.
B(t) is ABM, then has variance of

In simple terms, average has 1/sqrt(3), or about 58% of volatility.
Simple example: assume BTC/USD volatility of 100% per year. Expected volatility over 30 days should be sqrt(100 * 100 * 30/365) = 28.67%. However if the contract settles to the last day's average, for options pricing we should use volatility of sqrt(100 * 100 * 29/365 + 100 * 100 * 1/365 / 3) = 28.35%, slightly lower.
In conclusion: average settlement - interesting, but of little practical importance from pricing perspective.
P.S. Re: Atlas ATS - could not get their API to work, waiting for LedgeX.
Correct modelling of this is interesting for both options and futures pricing, as average process has obviously less volatility than "regular" process. How much less? Well, apparently I fell asleep during a class because I have no recollection of the formula until I recently researched it.
B(t) is ABM, then
has variance ofIn simple terms, average has 1/sqrt(3), or about 58% of volatility.
Simple example: assume BTC/USD volatility of 100% per year. Expected volatility over 30 days should be sqrt(100 * 100 * 30/365) = 28.67%. However if the contract settles to the last day's average, for options pricing we should use volatility of sqrt(100 * 100 * 29/365 + 100 * 100 * 1/365 / 3) = 28.35%, slightly lower.
In conclusion: average settlement - interesting, but of little practical importance from pricing perspective.
P.S. Re: Atlas ATS - could not get their API to work, waiting for LedgeX.
Updated Expiration Calendar
Happy New 2015 to volatility traders everywhere!
I have updated Expiration Calendar with expiration dates for all listed volatility futures in the world. What is new since the last update? Well, several things:
1 - Eurex added Variance Futures on Eurostoxx 50 Index (EVAR). Cannot say I'm excited about the product - CBOE tried to list variance futures twice without success.
2 - India VIX, weekly expirations on Tuesdays, 3 contracts listed at the time. Not sure who decided that NSE India needs weekly volatility contracts, instead of regular monthly contracts, like everything else on the exchange.
3 - Australia VIX, sadly the product did not attract much volume either. If I understand correctly, exchange's expiration calendar does not include expiration dates for AVIX, and I calculated them myself.
4 - Korea. After years of teasing, KRX finally listed VKOSPI futures last November. Volume is still low, but I hope that some of the KOSPI options liquidity will spill over to VKOSPI. Overall KRX seems to be on the product expansion mode. As FT reported yesterday the exchange "unveiled a 10-point plan to revive trading in Seoul, unveiling measures to relax daily price limits in its stock markets, introduce market making schemes for illiquid stocks and exempt derivatives market makers from a local transactions tax."
1 - Eurex added Variance Futures on Eurostoxx 50 Index (EVAR). Cannot say I'm excited about the product - CBOE tried to list variance futures twice without success.
2 - India VIX, weekly expirations on Tuesdays, 3 contracts listed at the time. Not sure who decided that NSE India needs weekly volatility contracts, instead of regular monthly contracts, like everything else on the exchange.
3 - Australia VIX, sadly the product did not attract much volume either. If I understand correctly, exchange's expiration calendar does not include expiration dates for AVIX, and I calculated them myself.
4 - Korea. After years of teasing, KRX finally listed VKOSPI futures last November. Volume is still low, but I hope that some of the KOSPI options liquidity will spill over to VKOSPI. Overall KRX seems to be on the product expansion mode. As FT reported yesterday the exchange "unveiled a 10-point plan to revive trading in Seoul, unveiling measures to relax daily price limits in its stock markets, introduce market making schemes for illiquid stocks and exempt derivatives market makers from a local transactions tax."
Dispersion Trading
Recent video from Tasty Trade on volatility dispersion trading. I think they quite downplayed the complexity of the trade, they don't mention proper weighting design to achieve either correlation or covariance mispricing, and their delta-based approach makes sense only for ITM options.
Other correlation resources:
Fundamental Relationship Between An Index's Volatility And The Correlation And Average Volatility Of Its Components, by Sebastien Bossu, Yi Gu
Dispersion Trading in German Option Market, by Jonas Lisauskas
Studying the Properties of the Correlation Trades, by Cayetano Gea Carrasco
Analysis and Development Of Correlation Arbitrage Strategies on Equities, Yujin Chloe Choi
and best for the last Dispersion Trading Reading List, from condoroptions.com


Other correlation resources:
Fundamental Relationship Between An Index's Volatility And The Correlation And Average Volatility Of Its Components, by Sebastien Bossu, Yi Gu
Dispersion Trading in German Option Market, by Jonas Lisauskas
Studying the Properties of the Correlation Trades, by Cayetano Gea Carrasco
Analysis and Development Of Correlation Arbitrage Strategies on Equities, Yujin Chloe Choi
and best for the last Dispersion Trading Reading List, from condoroptions.com
Weekly Options Selling, and Time-Risk Blindness
I would like to start today's post with a quote from a recent article discussing risk of earthquakes:
Even if we can comprehend a 30-percent chance of rain, or near-term odds like a coin flip, low-probability events are different. They have a “bewildering” effect on people, says Howard Rachlin, a professor emeritus of psychology at Stony Brook University. So we tend to lump them together; 1 in 10,000 sounds just as bewildering as 1 in 100,000. This is why people buy lottery tickets, even though the likelihood of winning is outrageously less likely than an event like a big earthquake in a seismically active region.“All low chances seem the same,” Rachlin says.
When it comes to living our lives today or making plans for next weekend, behaving as if low probability is essentially zero chance isn’t necessarily a bad thing. We would be paralyzed otherwise.
But stretch that low probability over time — which is how earthquake risk is estimated — and confusion with low probabilities morphs into complete incomprehension. If you live in an earthquake-prone place for 10,000 days, the cumulative probability gets higher and higher, approaching 1 in 1. Our minds, unfortunately, have a hard time keeping up.
“We don’t see how these small things add up when you do them over and over again,” says Fischhoff. In study after study—looking at compound interest, unsafe sex, driving without a seatbelt, floods, earthquakes — we underestimate such cumulative effects. It’s one of those cognitive shortcomings calling out for a name. Maybe it should be called something like time-risk blindness. From The Aftershocks by David Wolman.
Recently I have noticed a marked increase in the number of short volatility trading systems offered by vendors, and specifically trading strategies that sell weekly options. While short vol strategies have enjoyed certain popularity, they have grown (at least from what I see on the web) with increased liquidity and higher number of names in weekly options.
I will admit right away that I am not a fan of vendor strategies, especially in options, simply because disparate incentives between vendor and customer. Vendors usually charge fixed fees (usually monthly fees of $30-$100) for signals and recommendations that customer is supposed to execute in their own account. While vendor does not participate in the upside or downside of the trades they recommend, they cannot help but to want to keep their customers paying as long as possible. This is generally a good thing, but we should remember that these strategies are likely to be short-vol strategies - steady returns, low vol until vol spikes up.
This effect is particularly strong in weekly options, and I think is exacerbated by the time-risk blindness mentioned above. Vendors suggest profits of 1% per trade ( per week - 64% compounded after a year of trading ) implying approximately 1 in 100 "fair" chance of losing 100% of the account. Since 1 in 100 is 1 in 2 years of trading, this gives sufficient time for a vendor to build up a pretty chart and start collecting fees. This is also long enough for a client to start forming the time-risk blindness about real risks of the strategy.
In summary: please be extra careful about short-vol strategies with weekly options. It is very difficult to properly understand and appreciate the risks of such strategies.
Subscribe to:
Posts (Atom)
Weekly market report
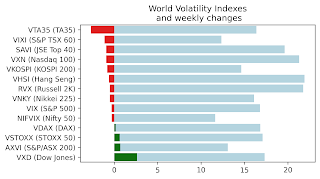
Wall st delivered a mixed bag of news with VIX, VNKY, and VSTOXX and their underlying markets almost unchanged. VXD - volatility index based...
-
 If you're working with daily data (without access to intraday data) and need to calculate volatility, then using close-to-close squared ...
-
As I am sure all of you know Russia has began a full scale war against my home country Ukraine. Please make no mistake - Putin's goal ...
-
VIX expiration day often coincides with particularly heavy trading activity in underlying SPX options. VIX settlement value, or VRO rarely m...
