Modeling Dynamics of Entire Implied Volatility Surface with Deep Learning

There is a very cool webinar coming up next week that I suggest everyone to register and attend link

Daniel Bloch, also often listed as Daniel Alexandre Bloch has contributed a lot of research on using ML for options pricing. Also Mr Block published a very thorough free textbook options pricing that I highly recommend to everyone - it reviews and evaluates most of the recent developments in options pricing.

Below I will review their paper from last year on the topic, sort of what you can expect from the webinar:

Here the authors are actually tackling the forecasting problem - how to forecast options prices. Since options prices are in constant basis movement - meaning time to expiration changes, moneyness changes, and the number of options is never fixed, they need to parametrize the entire volatility surface, and model those parameters. Here in the full "recipe":


1 - S&P data from 2012 to 2019 inclusive

2 - Fit SVI to each expiration slice

3 - Interpolate 8 fixed-maturity slices for 7, 14, 21, 30, 60, 90, 120, 180 calendar days to expiration, and 50 fixed log-moneyness "strikes" from -0.2 to +0.2 ( my comment: I don't understand why do they need fixed strikes, they should be fitting SVI to all strikes )

4 - 8 fixed maturity slices * 5 SVI parameters = 40 total parameters

5 - LTSM + Convolution NN, as below ( my comment : I think ...6,5 ... is a typo, should be  8,5 )


The authors note that the model seems to be under performing for very short maturities under 1 week, which makes sense because the model seem to be optimized for medium-term. Short maturities are dominated by noise, and would probably benefit from intraday data, or some different form of optimization.

Anyways - read the paper, attend the webinar, I highly recommend both. What should be notes is that this is a general recipe - the same can be applied to the VIX complex - either to futures only, or futures + options in static levels.


In 1939 and 1940 Mahatma Gandhi, the great Indian statesman wrote to Hitler, referring to him as "dear friend" , and writing that Hitler "... nor do we believe that you are the monster described by your opponents" 

Gandhi wrote to the British Viceroy in 1940 "This manslaughter must be stopped. You are losing; if you persist, it will only result in greater bloodshed. Hitler is not a bad man" 

In 1947 he stated "the Jews should have offered themselves to the butcher’s knife. They should have thrown themselves into the sea from cliffs."

I hope everyone can see how erroneous or misguided these statements were ... 

At the same time Winston Churchill wrote "Nations that went down fighting rose again, but those who surrendered tamely were finished," and called his compatriots: "War is horrible, but slavery is worse"

Be like Churchill, not like Gandhi! I am asking my US readers to make three phonecalls to

Congressman Mike Rogers, Armed Services Committee
+1 202-225-3261

Rep. Adam Smith, Chairman of the House Armed Services
+1 425-793-5180

Congressman Michael McCaul, Foreign Affairs Committee
+1 202-225-2401

to support Ukrainian struggle again Russian tyranny and imperialism. If you live in a different country I ask you to call your government representatives.

Trading Signals In VIX Futures

Marco Avellaneda has contributed tremendously to financial mathematics, and to volatility trading in particular, has passed away earlier this year. Here I will review one of his last papers on trading VIX futures. I think most readers of this blog have modeled VIX futures understand both the risks and potential profitability of roll strategies, and the most difficult part is balancing the two.

VIX futures strategies do not have the "level" dependency of, for example, index put selling strategies, and in general seem to be less complex. However regime shifting (from typical contango to infrequent backwardation) nature of these strategies too requires constant re-balancing to keep portfolio beta-neutral. 

For the strategy Avellaneda et al consider a 2-ETF portfolio: 1 month, and 5 month ( think VXX and VXZ )  A simple regression suggest portfolio short 1 month roll, and long 5 month roll, but as one can image that such static strategy is highly risky.

To construct a dynamic strategy the first step is to construct a mode ( robust form of mean ) , "typical" curve, based on fixed maturity 1-5 month futures, and calculate a regular 1-day AR model using least squares, which is our forecasting model for VIX returns. 

The interesting part comes how the trading signals are constructed. Let's denote R as returns simulated based on the AR model above, and X as the state vector, and a are portfolio weights. We are looking to maximize expected utility E[U(R(a))|X] by varying portfolio weights. To do this, we sample possible states X from our model, and calculate utility for a range of given portfolios, train neural network to map from a to E[U] 

Paper

Video lecture

There is a general recent trend in financial mathematics to use neural networks to approximate hard-to-compute functions, for example instead of running MC in real-time, train NN to approximate the function in a batch mode, and then use NN for pricing in real-time, which is significantly faster.

It is an active area of research, and in the near-future I hope to review this excellent cutting-edge paper on the subject.


When you think of "evil" what comes to mind? A demon from Exorcist? A Demogorgon from Stranger Things?

8 years ago Russian soldiers shut down flight MH17 killing 300 people. Immediately Russian media claimed that they shot down Ukrainian fighter jet, Russian terrorists made photos of themselves with debris in the background, looted luggage - and then proudly posted about it on social media. 

This is not the first time Russia has engaged in terrorism. They have shot down Korean Air Flight 007, and then denied any knowledge of it, and Korean Air Flight 902.

If you have Russian co-workers, ask them if they support the war. Do not take a generic "I am against all wars" as an answer. Ask if they consider Russia to be an aggressor, and Russia should de-occupy Donbas, Luhansk, and Crimea, and pay reparations for the war they started 8 years ago. If the answer is anything but yes you will know who are you working with. 

And please, call on your government representatives to provide more arms to Ukraine. We cannot defend ourselves with olive branches, and any agreement to peace Russian Federation will sign is worthless.


Weekly market report

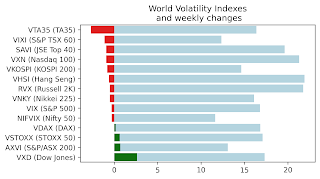
Wall st delivered a mixed bag of news with VIX, VNKY, and VSTOXX and their underlying markets almost unchanged. VXD - volatility index based...