ASX VIX Futures Launched

ASX finally launched futures on its volatility index. As I understand the futures were listed yesterday (Monday) but there were no trades. Today (Tuesday) 1 contract traded. Not a great start, but you have to start somewhere ....

I am having a hard time accessing data for the contract. On Bloomberg, the index is SPAVIX  <INDEX> , but the ticker for the futures is AS51VIX <INDEX> . I tried checking the prices just few minutes ago, but there was no data for any of the futures contracts, as if they don't exist. Edit: the current contract is VIA <INDEX> .

Exchange's own website is not much of a help either - futures summary table does not have the data for the VIX contract (futures root VI). I was able to figure out this non-linked page with the data:

S&P/ASX 200 Volatility Index Futures
Expiry Last Bid Ask Volume
Spot12.295
Nov 13 12.4513.10 0
Dec 13 12.00 11.90 12.10 1

The volume in other international volatility contracts on Tuesday was:
RTSVX (Russian volatility index) - 2 contracts
VHSI (Hong-Kong volatility index) - 19 contracts
VNKY (Nikkei volatility index) - 71 contracts


Two pretty good articles on HFT

These articles Jacob Loveless were posted few months ago on ACM (Association for Computing Machinery)  blog, but I just came across them.

Barbarians at the Gateways includes details on specific HTF trading strategy
Online Algorithms in High-frequency Trading provides high-level overview of some mathematics that is used for data analysis

Reading Up on Electronic Trading

I was reading Nerds on Wall Street, and came across the following paragraph:
David Whitcomb, a market microstructure economist at Rutgers University and coauthor of a 1988 book on electronic trading strategies faced ... skepticism selling his ideas to Wall Street. Finding no institutional backing, he joined forces with a computer scientist colleague to found Automated Trading Desk (ATD) in the proverbial garage in Charleston, SC. The firm reportedly grew from its first trade in 1990 to one of the leading electronic market participants, trading on average more than 200 million shares daily, or 6 percent of the volume on both the NYSE and NASDAQ.
Which got me interested in the Whitcomb's book. The work in reference - Transaction Costs And Institutional Investor Trading Strategies - proved to be quite difficult to find. It is not available for purchase anymore, and I could not find a local public library that carries the title. Thankfully a local university had one in their collection, and girlfriend borrowed a copy for me yesterday. Will keep you updated!

Update: finished reading Whitcomb's book. No content that I found useful.


DTN.IQ / IQFeed Caveat Emptor

I started working on a new strategy about a month ago and needed a cheap source of historical data for testing. DTN.IQ seem to fit the bill and budget, until yesterday I discovered that historical quotes data set that DTN.IQ provides foes not include all quotes, but only quotes at the time of a trade. For example, you have an illiquid stock that does not trade frequently.

made-up example

time,bid,ask,last
12:03:00,55.01,55.07,55.01  <- reported by the feed
12:04:00,55.02,55.08            <-no trade, not reported by the feed
12:05:00,55.05,55.16            <-no trade, not reported by the feed
12:06:00,55.05,55.16,55.10  <- reported by the feed

Even though quotes may be updating in between the trades, DTN.IQ does not provide that data.

Otherwise, my experience with the service has been satisfactory, and I will continue using the product for testing live data and historical data. 

What's going on with this blog

As you know I have not posted in a while. My current trading does not involve options, or any volatility-related instruments, and it became harder to come up with quality material. At the beginning of June I started trading, and had no time to follow volatility research. As of right now I will either update this blog less frequently with volatility-related news or expand coverage to include statistical arbitrage and machine learning. Good luck trading, and hedge your deltas!

VHSI Update and Forecast

VHSI May futures expired on 30th, last week. Unfortunately I was/am very busy with launching a new strategy into production and could not update the blog on time. Also somehow I missed the futures settlement value so I am using index settlement value instead in the Volatility Forecasts Tracker spreadsheet. Over May results were good, with my model providing better forecasts than the market and almost making up for the losses in April. Charts have been updated with the latest numbers.

My forecast for next expiration is for 16.29 vs futures value 17.25 (Monday settlement value).


VIX, VSTOXX June 2013 Forecasts

Yesterday all CBOE and Eurex volatility indexes settled - so forecasting results are in, and as always all the forecasts and results are logged in the Volatility Forecasts spreadsheet . The signals were all correct except for GVZ - Gold Volatility Index, which rallied on gold's quite unexpected decline.

The technical issues with data solved, and I have forecasts for all CBOE indexes.The forecasts are as follows:
VIX  13.47 vs 15.30 in the market
VSTOXX 17.50 vs 19.55
GVZ 23.63 vs 23.65  <- only 0.02 difference between market and forecast
VXEEM 18.77 vs 20.05
VXEWZ 19.39 vs 21.80
OVX 22.48 vs 24.75
VXN 14.55 vs 16.25

Weekly market report

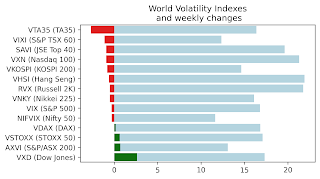
Wall st delivered a mixed bag of news with VIX, VNKY, and VSTOXX and their underlying markets almost unchanged. VXD - volatility index based...