After announcing new commodity volatility indexes back in March, CME announced they're actually launching futures and options on NYMEX WTI and COMEX Gold volatility in the fourth quarter. This is to be followed by launching volatility derivatives on Soybeans and Corn in the first quarter of next year.
There is no exact schedule of product launch - whether CME will launch futures first, and then introduce options, or launch futures and option simultaneously. I hope that the new products will succeed, although I have my reservation given many failures in volatility derivatives. What makes these contracts different is that GVX and OIV would be the first commodity volatility derivatives to be listed.
CME product webpage here, including historical data for all new indexes. Press release here.

Subscribe to:
Post Comments (Atom)
Weekly market report
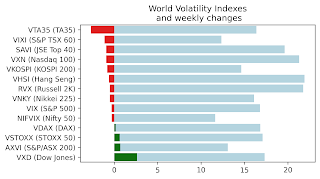
Wall st delivered a mixed bag of news with VIX, VNKY, and VSTOXX and their underlying markets almost unchanged. VXD - volatility index based...
-
 If you're working with daily data (without access to intraday data) and need to calculate volatility, then using close-to-close squared ...
-
As I am sure all of you know Russia has began a full scale war against my home country Ukraine. Please make no mistake - Putin's goal ...
-
VIX expiration day often coincides with particularly heavy trading activity in underlying SPX options. VIX settlement value, or VRO rarely m...

No comments:
Post a Comment